Broadridge Financial Solutions Stock Price and Value Analysis
Broadridge Financial Solutions (NYSE:BR) in our automated value investing analysis, with the cash flow history and price comparison below.
Key Facts
- Ticker: BR (NYSE)
- Current price: $181.41
- Sector: Industrials
- Industry: Specialty Business Services
- Dividend yield: 2.21%
Advertisement helps keep Trendshare free for most readers.
Hold-time calculator
Estimate how long you need to hold Broadridge Financial Solutions to reach your target.
BR Free Cash Flow Trend
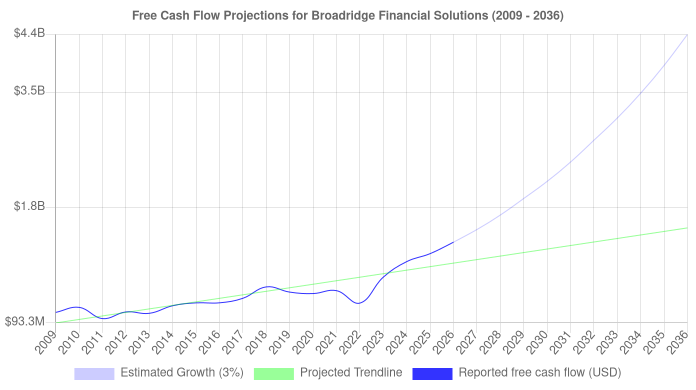
Based on historical returns, we believe that Broadridge Financial Solutions can grow its free cash at a rate of about 13%. That's positive!
| Advantages | Disadvantages |
|---|---|
|
|
Inside the BR Numbers
| BR Price (Broadridge Financial Solutions stock price per share) |
$181.41 | |
|
|
BR Fair Price (based on intrinsic value) |
$25.11 |
| BR Safety Price (based on a variable margin of safety) | $15.07 | |
|
Try your own return
The fair price above uses a 10.1% discount rate, the long-run US stock return (10.1% geometric, 1926 to 2025, from Bessembinder's working paper, updated 2026-11-09), and 2.5% terminal growth. A higher rate suits a higher return target and gives a lower value. Value per share: |
||
| PE Ratio versus Sector | 53% higher than other Industrials stocks | |
| PE Ratio versus Industry | 35% higher than other Specialty Business Services stocks | |
| Free Cash Flow Jitter | 28% | |
| Dividend Yield | 2.21% (tax impact) | Shares Shorted | 3,569,881 |
Insider Activity Summary
No open-market insider buys or sells are recorded for the last 12 months.
This stock has short interest! This means that people have shorted it.
Why does that matter? They've made a bet that price will decrease from where they bought it. Maybe there are financial problems, or maybe there's a value play.
As of the latest analysis, there are 3,569,881 shares shorted. With 112,549,753 shares available for purchase and an average trading volume over the past 10 trading days of 1,163,670, it would take at least 3.1 days for all of the short holders to cover their shorts.
Related guides: good annual rate of return · high-yield stocks · forecasting earnings growth
Free Cash Flow by Fiscal Year
How to read this: free cash flow in plain terms, free cash flow jitter.
Each year names the SEC filer that reported it, so a change of filer shows up here.
| Fiscal year | SEC filer (CIK) | Free cash flow (USD millions) |
|---|---|---|
| 2009 | 1383312 | 250 |
| 2010 | 1383312 | 325 |
| 2011 | 1383312 | 158 |
| 2012 | 1383312 | 257 |
| 2013 | 1383312 | 237 |
| 2014 | 1383312 | 350 |
| 2015 | 1383312 | 393 |
| 2016 | 1383312 | 393 |
| 2017 | 1383312 | 461 |
| 2018 | 1383312 | 631 |
| 2019 | 1383312 | 553 |
| 2020 | 1383312 | 532 |
| 2021 | 1383312 | 575 |
| 2022 | 1383312 | 389 |
| 2023 | 1383312 | 777 |
| 2024 | 1383312 | 1,008 |
| 2025 | 1383312 | 1,127 |
| 2026 | 1383312 | 1,298 |
Download the yearly data as CSV.
Cash Conversion
How to read this: what free cash flow is, why earnings matter.
Over the 12 fiscal years from 2011 to 2026 with positive net income, operating cash flow totaled $8,141 million against net income of $6,257 million, or 1.30 times.
In 2026, operating cash flow was 1.20 times net income, compared with 1.49 times for the earliest three years (2011 to 2013).
In 2026, capital expenditures were $67.2 million, 5.0% of operating cash flow of $1,346 million, which leaves an estimated $1,278 million after capex. Across the 12 years with reported capex, it averaged 7.1% of operating cash flow. This uses that year's own capital expenditures, not the five-year average behind the free cash flow table, so the two can differ.
Cash conversion in 2026 was 1.20, at least 0.25 under the 1.49 earliest three-year ratio. Gaps like this come from non-cash gains or from cash tied up in receivables, inventory or other working capital.
| Fiscal year | Net income (USD millions) | Operating cash flow (USD millions) | Capital expenditures (USD millions) | Operating cash flow / net income |
|---|---|---|---|---|
| 2011 | 170 | 191 | 29.2 | 1.13 |
| 2012 | 124 | 291 | 33.8 | 2.35 |
| 2013 | 212 | 271 | 38.2 | 1.28 |
| 2018 | 428 | 694 | 76.7 | 1.62 |
| 2019 | 482 | 617 | 50.6 | 1.28 |
| 2020 | 463 | 598 | 62.7 | 1.29 |
| 2021 | 548 | 640 | 51.9 | 1.17 |
| 2022 | 539 | 444 | 29 | 0.82 |
| 2023 | 631 | 823 | 38.4 | 1.31 |
| 2024 | 698 | 1,056 | 57.4 | 1.51 |
| 2025 | 840 | 1,171 | 43.8 | 1.40 |
| 2026 | 1,124 | 1,346 | 67.2 | 1.20 |
Where the Cash Went
How to read this: why companies buy back shares, dividend yield explained.
Over the 10 fiscal years from 2017 to 2026 with dividend or share repurchase facts, estimated free cash flow totaled $7,352 million. That estimate uses the average of up to five years of capital expenditures, not each year's own, so it is not a reported figure.
In the 10 of those years with dividend payment facts, dividends paid totaled $2,868 million, 39.0% of the estimated free cash flow of those years. Estimated free cash flow was at least the dividends paid in 10 of those 10 years.
In 8 of the 10 years, cash spent repurchasing shares was at least 5% of that year's estimated free cash flow, and in those years it totaled $2,334 million. Smaller amounts are left out of this sentence because they can be shares withheld to pay employees' taxes on stock awards.
In 2026, dividends and cash spent repurchasing shares together were $1,047 million, 80.7% of estimated free cash flow of $1,298 million.
| Fiscal year | Estimated free cash flow (USD millions) | Dividends paid (USD millions) | Cash spent repurchasing shares (USD millions) | Total returned (USD millions) | Total as a percent of estimated free cash flow |
|---|---|---|---|---|---|
| 2017 | 461 | 152 | 343 | 495 | 107.3% |
| 2018 | 631 | 166 | 277 | 443 | 70.2% |
| 2019 | 553 | 211 | 398 | 609 | 110.1% |
| 2020 | 532 | 241 | 69.3 | 310 | 58.4% |
| 2021 | 575 | 262 | 21.5 | 283 | 49.3% |
| 2022 | 389 | 291 | 22.8 | 314 | 80.5% |
| 2023 | 777 | 331 | 24.3 | 355 | 45.7% |
| 2024 | 1,008 | 368 | 485 | 854 | 84.7% |
| 2025 | 1,127 | 402 | 135 | 537 | 47.7% |
| 2026 | 1,298 | 444 | 604 | 1,047 | 80.7% |
Free cash flow here is an estimate: operating cash flow less the average of up to five years of capital expenditures. Cash spent repurchasing shares can include shares withheld to pay employees' taxes on stock awards. The entry n/a means the filings gave no usable figure, not that the amount was zero. Source: the company's annual reports to the SEC.
Revenue and Cash Margin
How to read this: earnings and margins.
Revenue was $2,073 million in 2009 and $7,477 million in 2026, a compound annual growth rate of 7.8% over 17 years.
Revenue rose 8.5% from 2025 to 2026.
Our estimated free cash flow was $1,298 million in 2026, 17.4% of revenue. In 2009 the estimated margin was 12.1%. This estimate charges each year with the average of up to five years of capital expenditures, so it is not the free cash flow the company reported.
| Fiscal year | Revenue (USD millions) | Estimated free cash flow (USD millions) | Estimated free cash flow / revenue |
|---|---|---|---|
| 2009 | 2,073 | 250 | 12.1% |
| 2010 | 2,209 | 325 | 14.7% |
| 2011 | 2,167 | 158 | 7.3% |
| 2012 | 2,304 | 257 | 11.2% |
| 2013 | 2,431 | 237 | 9.7% |
| 2014 | 2,558 | 350 | 13.7% |
| 2015 | 2,694 | 393 | 14.6% |
| 2016 | 2,897 | 393 | 13.6% |
| 2017 | 4,143 | 461 | 11.1% |
| 2018 | 4,330 | 631 | 14.6% |
| 2019 | 4,362 | 553 | 12.7% |
| 2020 | 4,529 | 532 | 11.7% |
| 2021 | 4,994 | 575 | 11.5% |
| 2022 | 5,709 | 389 | 6.8% |
| 2023 | 6,061 | 777 | 12.8% |
| 2024 | 6,507 | 1,008 | 15.5% |
| 2025 | 6,889 | 1,127 | 16.4% |
| 2026 | 7,477 | 1,298 | 17.4% |
Balance Sheet
How to read this: how debt and assets are compared, the current ratio.
In 2026, cash and equivalents were $403 million against total liabilities of $6,105 million, or 6.6% of total liabilities. Total liabilities include everything the company owes, not only borrowed money.
Total liabilities were 68.2% of total assets in 2026, compared with 55.0% in 2010, an increase of 13.2 percentage points.
Stockholders equity was $2,841 million in 2026, compared with $909 million in 2009, a rise of 212.5%.
Based on our estimated free cash flow, cash flow return on invested capital (CROIC) was 18.2% in 2026. Invested capital here is total assets less cash and current liabilities.
| Fiscal year | Total assets (USD millions) | Cash and equivalents (USD millions) | Total liabilities (USD millions) | Stockholders equity (USD millions) |
|---|---|---|---|---|
| 2009 | 2,775 | 173 | n/a | 909 |
| 2010 | 1,794 | 413 | 987 | 807 |
| 2011 | 1,904 | 242 | 1,107 | 797 |
| 2012 | 1,988 | 321 | 1,137 | 851 |
| 2013 | 2,018 | 266 | 1,202 | 816 |
| 2014 | 2,192 | 348 | 1,230 | 962 |
| 2015 | 2,365 | 324 | 1,440 | 928 |
| 2016 | 2,873 | 728 | 1,827 | 1,046 |
| 2017 | 3,150 | 271 | 2,146 | 1,004 |
| 2018 | 3,305 | 264 | 2,210 | 1,094 |
| 2019 | 3,881 | 273 | 2,753 | 1,128 |
| 2020 | 4,890 | 477 | 3,543 | 1,347 |
| 2021 | 8,120 | 275 | 6,311 | 1,809 |
| 2022 | 8,169 | 225 | 6,250 | 1,919 |
| 2023 | 8,233 | 252 | 5,993 | 2,241 |
| 2024 | 8,242 | 304 | 6,074 | 2,168 |
| 2025 | 8,545 | 562 | 5,890 | 2,655 |
| 2026 | 8,945 | 403 | 6,105 | 2,841 |
Price Versus Our Estimated Value
Free cash flow was positive in all 18 fiscal years we have for Broadridge Financial Solutions under its current SEC filer.
The latest three years average $1,145 million in free cash flow against $245 million for the earliest three, which is a sharp rise.
Year-to-year variability in free cash flow is uneven, measured at 28%.
Broadridge Financial Solutions is priced at $181.41, above our fair value estimate of $25.11 and its safe value of $15.07.
The dividend yield for Broadridge Financial Solutions is 2.21%.
Before you act on any of this, read what a margin of safety means and check the company's own filings.
Compared With Its Sector and Industry
How to read this: the price to earnings ratio.
Its trailing P/E ratio is 53% above the average for stocks in the Industrials sector.
Its trailing P/E ratio is 35% above the average for stocks in the Specialty Business Services industry.
A P/E ratio depends on trailing earnings, which one-time items can distort, so a lower P/E is not by itself evidence of value.
Closest Industry Peers
These are companies in the Specialty Business Services industry, the ones closest in market capitalization to Broadridge Financial Solutions, limited to companies whose pages we publish. The figures come from our latest data for each company.
| Company | Market cap (USD millions) | P/E | Dividend yield | Cash yield | Price versus our estimate |
|---|---|---|---|---|---|
| Broadridge Financial Solutions (BR) | 20,519 | 20.1 | 2.2% | - | 622% above |
| Rollins (ROL) | 18,080 | 34.7 | 1.9% | 1.1% | 58% above |
| Global Payments (GPN) | 24,302 | 164.0 | 1.2% | 1.9% | 28% below |
| Ritchie Bros. Auctioneers Incorporated (RBA) | 16,529 | 35.2 | 1.4% | 1.7% | 39% above |
| Fair Isaac Corporation (FICO) | 14,845 | 19.1 | - | 0.7% | 609% above |
| TransUnion (TRU) | 14,188 | 18.1 | 0.7% | - | 220% above |
| Fidelity National Information Services (FIS) | 13,315 | 3.9 | 6.6% | 10.6% | 62% below |
Industry labels are approximate, and companies in one industry can run quite different businesses, so a peer may not be a close match.
Ratios on different fiscal calendars are not strictly comparable, and a trailing P/E can be distorted by one-time items.
SEC Filer History
Every fiscal year on this page is reported by one SEC filer, CIK 1383312.
Each figure on this page comes from that filer.
Risks to This Analysis
How to read this: understanding investment risk.
- These figures are automated calculations from SEC filings and the recent price. They may contain errors, and they do not reflect lawsuits, management changes, or other events the filings do not show.
How This Page Is Made
- Latest annual report used
- Fiscal year 2026
- Price and market data last refreshed
- 2026-11-20
- Model assumptions last reviewed
- 2026-11-09
Company figures come from the annual reports (Form 10-K) that each company files with the SEC, read from the SEC EDGAR company facts data. The share price and other market data come from a market data provider.
Free cash flow here is operating cash flow minus capital spending. To keep one unusual year from swinging the result, each year is charged with the average of up to five years of capital spending, so the figure is an estimate and not the free cash flow a company reports.
The fair price is the present value of ten years of projected free cash flow plus a terminal value, discounted at 10.1 percent a year, the long-run return of US stocks, with 2.5 percent growth after year ten. The figures on this page are estimates, not advice.
This analysis covers US companies that file 10-K annual reports. Free cash flow describes banks, real estate investment trusts and funds poorly, so treat their figures with extra caution. In the cash returned and balance sheet tables, a value of zero is treated as a gap in the data, not as a real zero.
Read the filings yourself: BR annual reports (10-K) on SEC EDGAR. To try your own growth rate, use the intrinsic value calculator on this page. Our editorial standards explain how Trendshare handles its sources and corrections.
Advertisement supports free stock analysis content.
Questions to Answer Before You Invest in BR
Does Broadridge Financial Solutions have a coherent story? Does it have a plan to continue to make money? Is it worth your time? Only you can decide where to go from here. Our investment guide helps you ask the right questions, including how to buy stocks. Use these research links for more information.
Worked example: BR
This example shows how we apply the Trendshare checklist to BR: earnings power, cash generation, valuation, and margin of safety.
We check: business quality, free cash flow, P/E, and margin of safety.
-
Step 1 — Snapshot
- Price: 181.41
- Market cap: $21B
- EPS: 9.03
-
Step 2 — Valuation checks
- P/E: 20.09
- FCF yield: —
- Date checked: Nov 20, 2026
-
Step 3 — Margin of safety
- Compare price to fair value and safety price.
- Look for durable cash generation and reasonable leverage.
- Decide if it passes your personal checklist.
Most Popular Articles
How Does Portfolio Churning Affect Your Returns?
Insider Buying as a Conviction Signal
What is Market Capitalization?
What is Cash Return on Invested Capital?